 Polytoolhub
Data API
Replay your trading strategy against historical order books, with explicit fill and latency assumptions.
- Data coverage Order books · Trades · Prices
- Access API
Find your toolkit
Replay strategies or recorded execution, compare scenarios and inspect modeled fills. Find raw historical inputs in Historical data and forward simulations in Paper trading.
Check the replay window and how the engine handles fees, spread, missing data and available depth.
Replay your trading strategy against historical order books, with explicit fill and latency assumptions.
Retrieve historical Polymarket books and run either tick-level execution simulations or faster bar-based signal backtests in Python.
Use a Rust-native Polymarket adapter inside NautilusTrader for live feeds, signed execution and strategy research.
Download historical market-day bundles or replay books and trades in a browser to inspect execution costs at a chosen size.
Trade Polymarket with configurable order-book panels, automatic journaling and risk rules that can block new buys after a limit is reached.
Run local strategy agents that compare venue prices, simulate trades and automate two-leg arbitrage or one-sided value betting.
Trade manually or copy selected Polymarket wallets with proportional sizing, execution filters, position exits and historical copy simulations.
Replay crypto Up/Down markets using historical order-book depth and timestamped data.
Copy Polymarket wallets in Telegram with fixed or percentage sizing, isolated sub-wallets, separate buy/sell controls and detailed execution notifications.
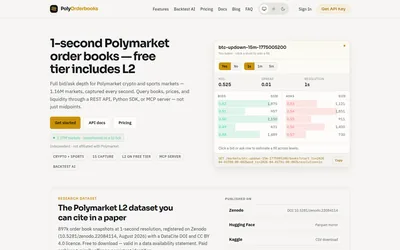
Query historical Polymarket crypto and sports order books at 250 ms resolution, or replay a crypto strategy against recorded depth.
Research whale activity, build wallet alerts and test copying in Orca, with a separate API plan for historical data, webhooks and exports.
Research Kalshi markets in chat, backtest rules, monitor positions and cross-check Polymarket prices without delegating trade execution.